

ANAROCK Research projects over USD 3.5 billion in mall investments over three years
MUMBAI, Dec 17 (The CONNECT) — As shopping malls across the United States shutter stores, seek rezoning approvals and brace for obsolescence, India is witnessing the reverse — packed malls, rising rentals and a flood of global capital chasing scarce Grade-A retail space.
According to ANAROCK Research, Indian shopping malls are set to attract over USD 3.5 billion in capital inflows over the next three years, even as Western retail markets struggle with oversupply and declining footfalls. Since 2020, the US has recorded a net closure of nearly 1,200 mall stores, forcing almost 40 percent of vacant malls to undergo rezoning or repurposing, despite a surge in new store openings over the past two years.
India’s momentum is being powered by structural demand rather than cyclical recovery. More than 88 foreign brands entered the Indian retail market between 2021 and the first nine months of 2025, with several more global players actively scouting for space in top-tier malls. However, availability remains severely constrained. Existing Grade-A malls are operating at near-full capacity, reporting 95–100 percent occupancy with long waitlists in prime catchments.
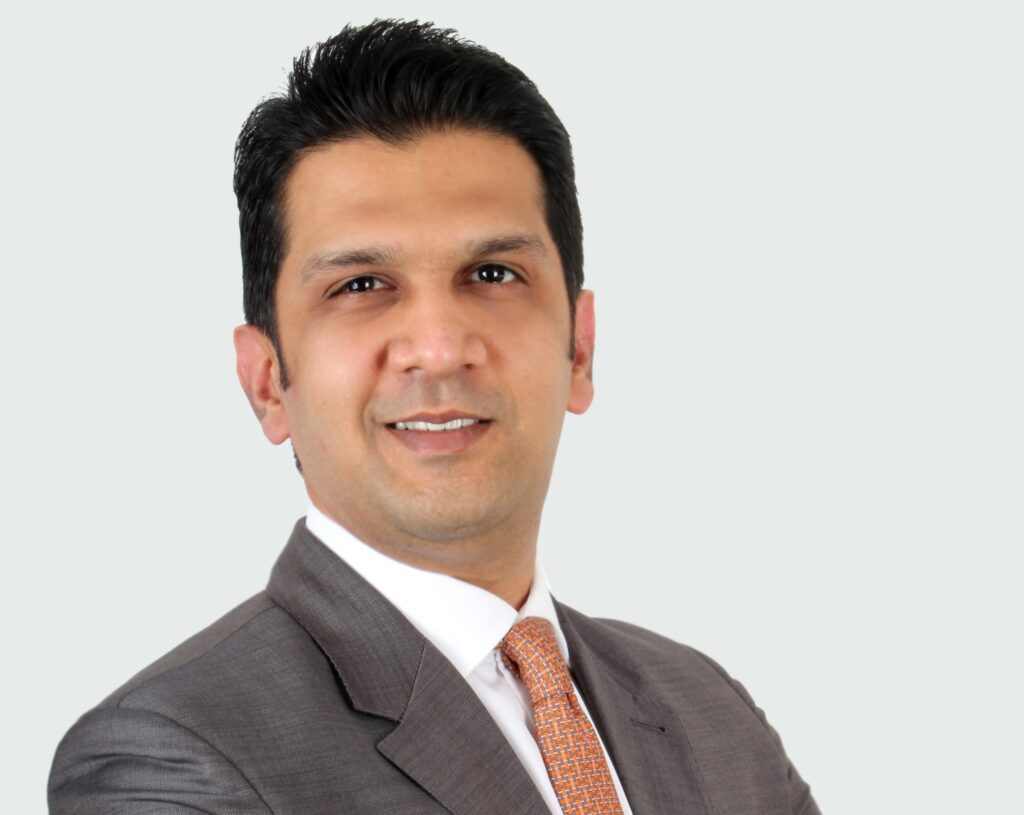
Anuj Kejriwal, CEO – Retail Leasing and Industrial & Logistics, ANAROCK Group, said the scale of India’s demand–supply imbalance is rare in global retail. “Over the next three years, Indian malls are expected to attract more than USD 3.5 billion in investments. Foreign brands are expanding aggressively, but the supply of institutional-grade retail assets remains extremely limited,” he said.
India’s per-capita retail stock remains among the lowest globally. Tier-I cities offer just 4–6 sq ft per person, Tier-II and III cities 2–3 sq ft, while Grade-A mall space stands at a mere 0.6 sq ft per capita. By comparison, the US averages nearly 23 sq ft per person, while China exceeds 6 sq ft. This disparity, coupled with per-capita incomes nearly doubling over the past decade, has created a demand environment that continues to favour landlords.
Unlike Western markets where e-commerce has hollowed out physical retail, Indian malls have evolved into experience-led destinations anchored by entertainment, dining and social interaction. Major malls routinely record weekday footfalls exceeding 20,000, rising beyond 40,000 on weekends. Food, beverage and entertainment now account for 30–35 percent of footfalls, reinforcing resilience against online disruption.
Investor appetite has further sharpened following the 2023 listing of Blackstone-backed Nexus Select Trust REIT, which owns 19 malls housing over 1,000 brands and generates more than ₹1,600 crore in annual net operating income. The listing established retail-led REITs as a transparent and scalable asset class, with at least two more retail REITs expected to enter the market by 2030.
India’s Grade-A malls typically deliver internal rates of return of 14–18 percent — nearly double those in many Western markets — supported by rental escalations, revenue-sharing models and consistently low vacancy levels.
“In the US and Europe, malls are battling oversupply and declining relevance,” Kejriwal said. “India, by contrast, combines limited quality supply with rising incomes, strong footfalls and rapid brand expansion. That makes it one of the few global retail markets where the future remains decisively physical.”